Blog Information
- Posted By : Victoria Hodgson
- Posted On : Nov 11, 2026
- Views : 5
- Category : Soccer
- Description :
- Location : USA
Overview
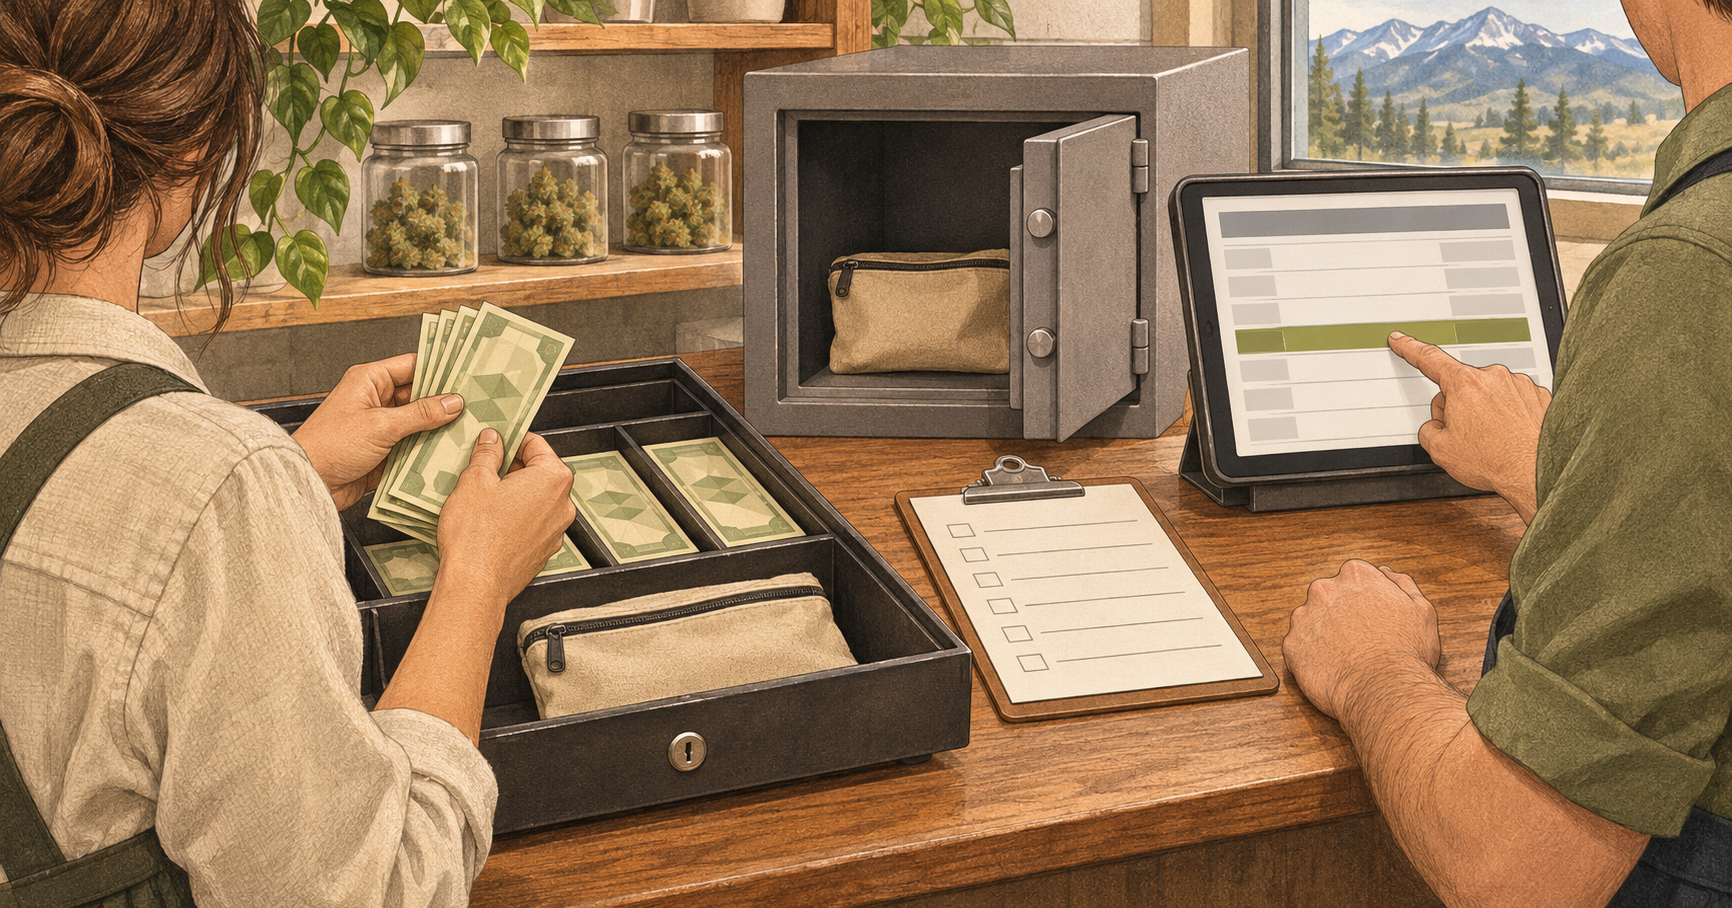
A drawer shows a shortage after an employee moves cash to the safe. The employee remembers making the drop, but the reviewer cannot find a corresponding record. Before changing the balance, the team needs to establish where the cash went and how the movement was recorded.
For Montana dispensaries, auditing transfers means tracing money between identified locations and comparing the evidence with a physical count. A drawer total alone cannot explain whether a movement was completed, omitted, or assigned to the wrong destination.
If your software search includes “cannabis wholesale platform Montana,” evaluate retail cash controls separately from wholesale workflows. Ask the vendor to demonstrate a drawer transfer, its destination record, and the process employees use when the two do not agree.
Define the movement before checking the balance
Identify what physically happened. Cash moved between registers, a drop went to the safe, an employee replenished change, or money left for another documented purpose. Record the source and destination before deciding which software action should represent it.
Dutchie’s cash management documentation distinguishes register transfers, cash drops, withdrawals, deposits, and balance adjustments. It directs users to reserve balance adjustments for correcting errors and use the appropriate movement action when adding or removing cash. Verify the equivalent controls in your own POS.
Keep cash movements separate from sales and refunds
An internal movement does not represent a new customer purchase. Likewise, moving existing cash should not be recorded as a refund merely to reduce the drawer balance.
Classify the physical event before selecting the action. If the available options do not clearly match it, ask the system owner for the documented procedure rather than choosing whichever option produces the desired total.
Establish the drawer and session under review
Confirm the store, register, employee assignment, opening amount, and review period. Check which session contains the movement and whether the corresponding destination activity falls within the same comparison.
Pay attention to shift boundaries. A transfer recorded near handover can appear in different session reports depending on the system’s rules. Inspect the actual records and timestamps instead of relying on employees’ recollection of the shift.
Keep the opening count available. If the starting amount was uncertain, document that separately so the investigation does not automatically attribute the entire difference to a later transfer.
Trace the transfer from source to destination
Find the source record and compare its amount, destination, timing, and responsible employee with the handoff evidence your store retains. Locate the receiving record or safe activity through the documented workflow.
Check whether the cash physically reached the intended destination. A transfer entry demonstrates what was recorded; the destination count and handoff confirmation help establish what occurred.
Match evidence without entering the transfer twice
Ask whether the POS creates linked entries automatically or requires separate actions for the receiving location. Review the provider’s documentation before creating another record.
Verify the existing transaction before entering a second movement. A receiving total that appears incomplete may need investigation rather than another deposit. Preserve the original reference so any follow-up remains connected to the same event.
Count the cash and explain the expected balance
Count the physical cash independently, then compare it with the expected balance for the defined period. Reconstruct that expectation from the opening amount, applicable cash payments and refunds, and documented additions or removals.
Use the system’s definitions to determine which movements are already included in its totals. Otherwise, a reviewer might subtract a cash drop again after the report has already accounted for it.
An internal transfer changes where the store holds its money. Keep that movement distinguishable from sales revenue when reviewing the receiving location.
Check both drawers before accepting an offsetting difference
Consider a hypothetical shortage in one register and a matching excess in another. That pattern warrants checking whether the transfer was assigned to the wrong drawer.
Matching amounts are a clue, not proof. Compare transaction references, timing, handoff evidence, and physical counts before deciding that the differences belong together. Unrelated mistakes can produce similar amounts.
Investigate missing, duplicated, and misclassified movements
Start by checking whether an expected record is absent, entered more than once, or recorded under an unsuitable action. Inspect related deposits, withdrawals, and close-out activity where relevant.
Ask the employee involved to explain the sequence, then compare that account with the retained evidence. Record uncertain details as unresolved rather than presenting recollection as a confirmed transaction history.
Choose the supported correction process after identifying the error. These checks are operational recommendations; they do not establish Montana legal requirements or prove the capabilities of a particular platform.
Preserve the original discrepancy before correcting it
Save the original physical count, expected balance, affected references, and investigation outcome. Identify who authorized the correction and why it was appropriate.
Do not replace an unexplained shortage with an unexplained adjustment. The record should allow another reviewer to understand the original observation and the action taken.
After an authorized correction, repeat the relevant comparison. Confirm its effect at the source and destination, including whether any related exception remains open.
Assign responsibility for the handoff and review
Define who records the outgoing movement, confirms receipt, and reviews a disagreement. Where staffing allows, have someone other than the employee entering the transfer verify the supporting evidence.
Make those responsibilities practical for the store’s staffing. The procedure should explain what happens when the usual manager is unavailable and which decisions require escalation.
Keep access aligned with assigned work. Ask which roles can initiate movements, inspect records, and make corrections, then verify those permissions in the actual setup.
Carry unresolved transfers into the next shift clearly
A handoff should identify the affected drawer, amount, transaction reference, completed checks, and next action. Specify where the cash is believed to be and which part of that account remains unverified.
Every unresolved movement needs a named owner. A general note saying “cash issue” leaves the next shift to repeat the investigation and increases the chance of another entry being made without context.
Test the process before the next cash review
Select an existing movement and ask another employee to trace it from the source record through the handoff evidence to the destination. Have them explain how it affects the relevant balances.
Note any missing access, unclear action names, or unsupported assumptions. Resolve those gaps with the responsible manager or provider and update the procedure.
Before the next review, repeat the exercise with a different employee. Accept the process when the cash movement and resulting balances can be explained from the records without depending on the original employee’s memory.